For Information About Legal Services, Contact Us on WhatsApp

Section 138 Of The NI Act – Cheque Bounce Case Judgement

Cheque Bounce

Cheque Bounce Case – Signature Dispute An Undisputed Signature Alone Cannot Lead To Conviction Under Section 138 Of The NI Act – Excellent Cheque Bounce Case Judgement By The Punjab & Haryana High Court Parveen Mehta Versus Vishal Joshi – Punjab and Haryana High Court Cheque Bounce Case Complaint A check for Rs.85,000/- was written and then returned with “insufficient funds” written on it. Under Section 138 of the Negotiable Instruments Act of 1881, the complaint was filed. A legal notice was disseminated. The cheque was issued only as security and repaid – Respondent’s Defense The respondent argued that the security cheque was misused. According to the respondent, he only borrowed Rs.5,000/- from the complainant and repaid it within the prescribed time frame. However, despite repeated requests, the complainant did not return the check. Later, he was shocked to discover a court summons for Rs. 85,000/- and a complaint against the respondent. Income Tax Returns of the Complainant as defense evidence The respondent relied upon the testimony of an official of the Income-tax Department and the income-tax returns filed by the complainant. Further evidence was adduced to show that the complainant was acting as a money lender. He filed a number of complaints under Section 138 of the Act by misusing security checks. If the amounts lent by him on the loan are compared with his income-tax returns, the loan amount was much higher. Acquittal of Respondent in Cheque Bounce Case by the Trial Court According to the trial court, the respondent’s argument was convincing, and the complainant couldn’t prove his case. The trial court also found the respondent not guilty because it is clear that the respondent signed the check. Appeal against the Trial Court’s Order by the Complainant In the High Court Appeal, the complainant said that there is no question that the respondent signed the check. Section 138 of the Act says that it is not part of the process to figure out how much money the complainant has. He went to a higher court to challenge the decision of the lower court. According to him, the respondent should have been held accountable for failing to pay off his debt by cashing the check given to him. The appeal was dismissed by the High Court The High Court ruled that the applicant’s arguments don’t warrant an appeal. The trial court has not determined the financial capability of the petitioner for lending the loan. The respondent provided evidence to support his claim that the security deposit check was misused and that he repaid Rs. 5,000. The undisputed signatures of the respondent on the cheque are not sufficient for conviction under Section 138 of the Act. Section 138 of the Act requires that the cheque be issued for debt or other liability. The respondent rebutted the Section 139 presumptions against him, and the appellant failed to meet his burden. The view taken by the trial court is a plausible view. Download Full Judgement Legal Disclaimer: The information contained in this blog post is for general information and educational purposes only. Nothing contained in this blog post should be construed as legal advice from The Aran Law Firm or the individual author, nor is it intended to be a substitute for legal counsel on any subject matter.
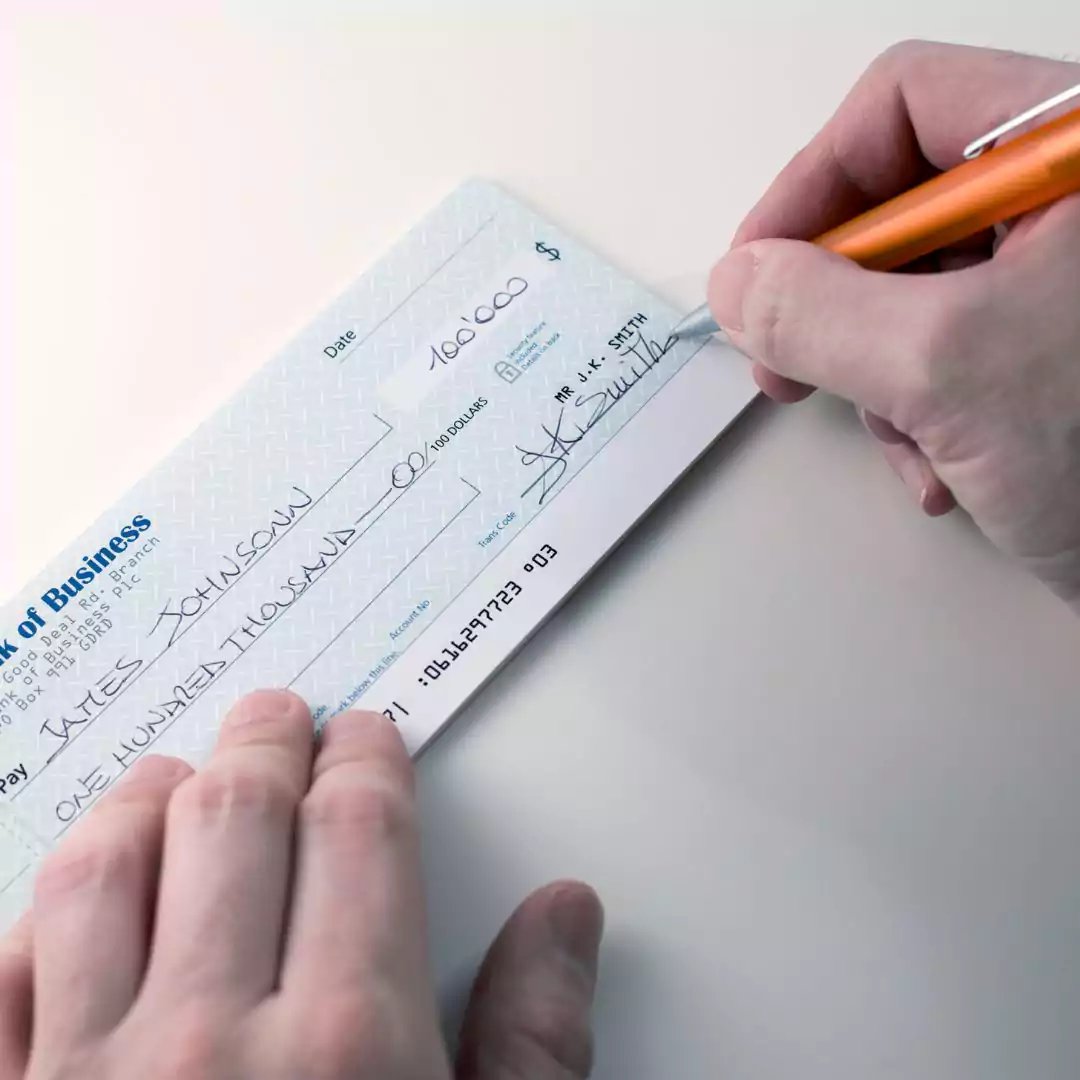
8 Most Important Reasons For Dishonor Of Cheques

Reasons For Dishonor Of Cheques

Dishonor of the cheques Is The Most Common Financial Criminal Offense Committed During the Business Transactions. Before Going Into Technicalities, Let Us Understand A Few Standard Things One Must Keep In Mind While Drafting A Cheque. A Dishonor of Cheques Is A Negotiable Instrument Used As A Mode Of Payment In Business Transactions. It Is The Most Convenient Mode Of Payment Done Through A Bank As An Intermediary. It Is Also The Most Crucial Source Of Evidence In All Financial, Legal Matters – Reasons For Dishonor Of Cheques. There Are a Few Things One Should Keep In Mind While Drafting The Cheque To Avoid Any Corrections Or Rejections Of The Cheque:  Appropriate Date In The Format DD/MM/YYYY Valid Signature Name Of The Person Against Whom The Cheque Is Drawn Amount In Figures And Words With Correct Spelling Just In Case Any Alterations Are Made In The Cheques, Nature Against The Alteration Is Mandatory. Also, Make Sure You Have Funds In The Account. Having Said That, If Anything Goes Wrong With The Cheque, The Banks Will Not Process/Honor The Cheque, And You Will Receive A Message On Your Registered Mobile Number That The Particular Cheque Is Dishonored. Just Imagine, We Deposit The Cheque In The Bank To Receive An Intimation Of Dishonor Amounts To Mental Harassment. A Cheque With Fewer Amounts Might Not Make A Big Difference, But The More Considerable The Amount, The More Is The Risk Against It. When You Give Cheques Against The Cheque You Deposited In The Bank, Only To Know That It Is Dishonored Will Damage Your Reputation In The Business And Give Rise To Legal Consequences And Procedures. Most People Aren’t Aware Of Why Cheques Are Dishonored, But It Is Essential To Know This To Help You File A Case Against That Person. Most Reasons For Dishonor Of Cheques Insufficient Funds: One Of The Significant Reasons For Dishonor Is The Lack Of Funds In The Account Of The Drawer. Suppose The Cheque Amount Exceeds The Bank Account Amount. It Is Very Embarrassing As The Bank Cannot Honor The Payment, And Consequently, The Cheque Is Dishonored. Also, Suppose The Drawer’s Account Has An Arrangement Of Passing Cheques Of Limited Amounts. In That Case, The Bank Will Not Process Any Amount Exceeding That Amount. Material Alterations Made On The Cheque: Once A Cheque Is Drawn, Any Alterations Made On The Cheque, Overwriting On The Cheque, Or Changes Made On The Face Of It, Will Undoubtedly Result In The Cheques. Signature Issues: A signature Plays An Integral Part In The Authentication And Verification Of The Cheque. Any Discrepancy Or Irregularities Found On The Signature Will Lead To Immediate Dishonor Of The Cheque. Post-Dated Or Stale Cheques: Date Plays A Vital Role In The Cheque. If The Cheque Is Presented Before The Due Date Mentioned On The Cheque, It Is Called A Post-Dated Cheque. If The Cheque Is Presented Three Months From The Cheque’s Date, It Is Called A Stale Cheque. In Either Case, The Bank Will have The Cheque As The Bank Will Not Accept These Cheques. Stop Payment Instructions: If The Drawer Orders The Bank To Issue A Stop Payment Of The Cheque, The Bank Will Not Clear It. In This Case, The Drawer’s Bank Will Not Initiate The Payment For The Said Amount. Closed/ Frozen Account If An Account Is Closed Or Is Inoperative For A Very Long Time, Then The Banks Will Not Honor The Cheques For Security Reasons. If The Government Freezes An Account, No Transactions Will Be Allowed On Those Accounts. Death/ Insolvency/ Lunacy Of The Drawer: Suppose The Banks Receive An Intimation Of Death, Insolvency, Or Lunatic Condition Of The Drawer. In That Case, Any Cheque Issued In That Time Frame Will Be Dishonored. Invalid Account Number This Is The Most Common Mistake Committed While Drafting The Cheque- An Invalid Account Number. Every Digit Matters While Writing A Cheque. Even One-Digit Being Misplaced Will Cause Much Loss To The Parties. Hence, The Teller Will Check The Account Number, Verify It And Then Clear The Cheque. Legal Standpoint: According To Section 138 Of The Negotiable Instrument Act, 1881– Dishonor Of Cheques For Whatever Is A Criminal Offense Punishable by Up To 2 Years Of Imprisonment Or a Fine, Which Can Be Twice The Amount Of a Cheque Or Both. Not Only Will The Drawer Be Subject To Legal Damages, But This Will Also Affect His Credit Score And Be A Hindrance In Any Other Banking Or Loan Transactions. At Times, The Banker Will Stop The Cheque Facility And Cheque Books To The Account Holder. However, Suppose The Drawer Makes Payment Of The Dishonored Cheque Amount Within 15 Days From The Date Of Receipt Of The Notice. In That Case, The Drawer Does Not Commit Any Offense. Otherwise, The Payee May File A Complaint In The Court Of The Jurisdictional Magistrate Within One Month From The Date Of Expiry Of 15 Days Prescribed In The Notice – Reasons For Dishonor Of Cheques. Legal Disclaimer: The information contained in this blog post is for general information and educational purposes only. Nothing contained in this blog post should be construed as legal advice from The Aran Law Firm or the individual author, nor is it intended to be a substitute for legal counsel on any subject matter.

Nine Most Important judgements to defend the Cheque Bounce Case

Reasons For Dishonor Of Cheques

Here are nine key cheque bounce case laws decided by trial and appellate courts. These rulings can provide essential guidance for proving your side against cheque bounce case under the Negotiable Instruments Act, 1881. 1. Cheque Issued as Security for a Loan In Shriram Transport Finance Co. Ltd. v. Mahadevaiah, Laws (KAR) 2015 – 7 – 279, the complainant had to prove that the bounced cheque was issued to discharge a legal liability, whether in full or part. Under Sections 138 and 139 of the Negotiable Instruments Act, the law presumes the cheque was issued to settle a debt unless the accused proves otherwise. In this case, the accused claimed the cheque was issued as security for a loan back in 1999, which was repaid, but the cheque was not returned. 2. Loan Repaid, But Security Cheque Not Returned In Vasanthakumar v. Vijayakumari, Laws (SC) 2015-4-79, the accused claimed they repaid the loan, but the complainant did not return the security cheque. The court found this defense weak, as it was unsupported by evidence. Merely having a printed date on the cheque did not conclusively prove it was issued in 1999. The court also ruled that if the complainant fails to prove the existence of a legally recoverable debt, the acquittal of the accused is justified, as seen in K. Subramani v. K. Damodara Naidu, (2015) 1 SCC 99. 3. Uncertainty About the Cheque Issuer In John K. Abraham v. Simon C. Abraham, (2014) 2 SCC 236, the complainant was unsure who wrote the cheque and was unaware of the details of the transaction. Under these circumstances, the court ruled that convicting the accused would not be proper. 4. Failure to Provide Material Facts In H. Manjunath v. A.M. Basavaraju, ILR 2014 Kar. 6572, the court acquitted the accused due to the complainant’s failure to provide essential details. The complainant did not clearly state when the loan was given. Additionally, inconsistencies in the handwriting and ink used in the cheque entries further justified the acquittal. Section 141 of the Negotiable Instruments Act also emphasizes corporate criminal liability, making companies liable under certain conditions. 5. Cheque as Evidence of Loan Recovery In Late Patel v. Sharanbasappa, Laws (KAR) 2012-7-473, the court confirmed that a cheque issued in full or partial payment of a debt could be treated as a primary loan document. The presumption under Section 139 stands unless the accused provides evidence to rebut it. The Rangappa v. Mohan, AIR 2010 SC 1898 case reaffirmed this legal presumption in favor of the cheque holder. 6. Defenses Available to the Accused in Cheque Bounce Cases In Kumar Exports v. Sharma Carpets, (2009) 2 SCC 513, the court clarified that an accused has two main defenses in cheque bounce cases. The accused can either: Argue that the consideration or debt did not exist, or Demonstrate that it is highly probable no debt or liability existed, making it unreasonable for anyone to assume otherwise. The accused does not need to prove this beyond a reasonable doubt—only by the balance of probabilities. Once the accused provides rebuttal evidence, the burden of proof shifts back to the complainant. 7. No Proof of Lost Cheque In Bangalore v. M/S. Uphar Fashions, Laws (KAR) 2008-9-6, the accused claimed they lost a cheque but failed to provide any evidence to support this claim. The court ruled in favor of the complainant, as the statutory presumption favored them. 8. Burden of Proof Lies with the Complainant In John K. John v. Tom Varghese, 2007 AIR SCW 6736, the court stated that presumptions under Sections 118 and 139 of the Negotiable Instruments Act can only be rebutted by considering all material evidence. The accused does not need to prove their defense beyond a reasonable doubt, nor are they required to testify. In Krishna Janardhan Bhat v. Dattatreya G. Hegde, AIR 2008 SC 1325, the court noted that it can also consider the conduct of the parties. 9. Presumptions Under the Negotiable Instruments Act In Hiten P. Dalal v. Bratindranath Banerjee, AIR 2001 SC 3897, the court emphasized that the presumptions under Sections 118(a) and 139 must be raised as soon as the cheque’s execution is admitted or proven by the complainant. The burden then shifts to the accused to prove otherwise, showing that the cheque was not issued to settle a debt. While these presumptions are rebuttable, they are crucial for the complainant’s case. Conclusion Successfully navigating cheque bounce cases requires a solid understanding of the law and the relevant case precedents. These landmark rulings offer insight into the defenses available to the accused and the burden of proof that applies to both parties. If you are involved in a cheque bounce case, seeking expert legal guidance is essentia

Disclaimer & Confirmation

Please read before continuing

Under the rules of the Bar Council of India, Aran Law is prohibited from soliciting work or advertising. By clicking “I Agree”, you acknowledge the following:

Please read and accept our  Privacy Policy.